Dimitri Bianco · Video summary
Partial Moments in Quantitative Finance
Explore partial moments for advanced quantitative finance, enabling nonlinear analysis, robust risk modeling, and dynamic portfolio optimization beyond traditional methods.
 Watch on YouTube ↗
Key takeaways
- 💡Partial moments offer a flexible framework to decompose variance, allowing for a more nuanced understanding of risk by focusing on specific regions of return distributions (e.g., downside vs. upside).00:45
- 🚀Explore the R package 'NNS' to experiment with partial moment calculations and their equivalences to standard statistical measures.02:19
- 🎯By adjusting the 'degree' and 'target' in partial moment calculations, one can generate CDFs with fatter tails, effectively modeling varying degrees of risk aversion or risk-seeking behavior.06:46
- 📈Partial moments directly enable stochastic dominance analysis, providing a rigorous method to identify and select portfolios of securities that are not dominated by others, based on risk preferences.08:45
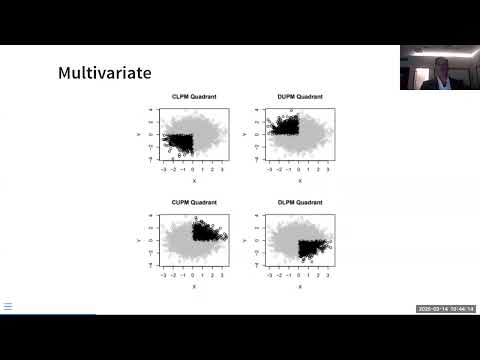
- 🔍Multivariate partial moment matrices (co-lower, co-upper, and divergent) provide a structured way to recreate and analyze the covariance matrix, offering deeper insights into inter-variable relationships.12:40
- 📊New metrics for correlation and dependence can be derived from partial moment quadrants, offering robustness for nonlinear signals beyond traditional measures like mutual information or distance correlation.17:30
Chapters
- 0:12🎯 Introduction to Partial Moments
- 1:28🎯 Mathematical Definition of Partial Moments
- 2:10🎯 Properties and Equivalences of Partial Moments
- 7:04🎯 Partial Moments in Distribution Analysis
- 12:40🎯 Multivariate Partial Moment Matrices
- 22:50🎯 Time Series Forecasting and Nonlinear Regression
- 28:39🎯 Applications in Stress Testing and Portfolio Optimization
- 31:18🎯 Utility Theory and Personal Risk Profiles
- 42:51🎯 Portfolio Clustering and Stochastic Dominance
- 47:04🎯 Risk Measurement Using Dispersion Metrics
- 49:23🎯 Financial Data Applications and GPT Integration
The digest
High Level Overview
This presentation explores the concept of partial moments—statistical measures focusing separately on gains and losses—and their extensive utility in quantitative finance. Originating as an advancement over conventional variance-based methods, partial moments offer a refined lens for understanding risk, dependence, and portfolio construction. The discussion covers foundational theory, multivariate expansions, nonlinear regression methods based on partial moments, and concrete finance applications such as stress testing, utility theory, and portfolio optimization. This material is valuable for quantitative analysts, risk managers, and portfolio theorists seeking more nuanced, empirically grounded approaches to measuring risk and asset dependence.
Keep reading in The Digest
The full 6-minute article, 14 more sections, and every new episode from Dimitri Bianco and the creators you follow.
- Structured Deep Dive
- Introduction to Partial Moments and Their Origins
- Statistical Equivalences and Basic Properties
- Partial Moments as a Framework for Distribution Tail Emphasis & Stochastic Dominance
- Multivariate Partial Moment Matrices and Covariance Reconstruction
- New Measures of Dependence and Correlation Based on Quadrant Partitioning
- Nonlinear Regression via Iterative Partitioning of Partial Moment Quadrants
- Financial Applications: Stress Testing and Portfolio Construction
- Advanced Portfolio Theory and Clustering Techniques
- Time Series Forecasting and Synthetic Data Generation
- Practical Tools and Real-World Implementations
- Summary of Frameworks & Models
- Practical Implications & Takeaways
- Action-Oriented Summary
